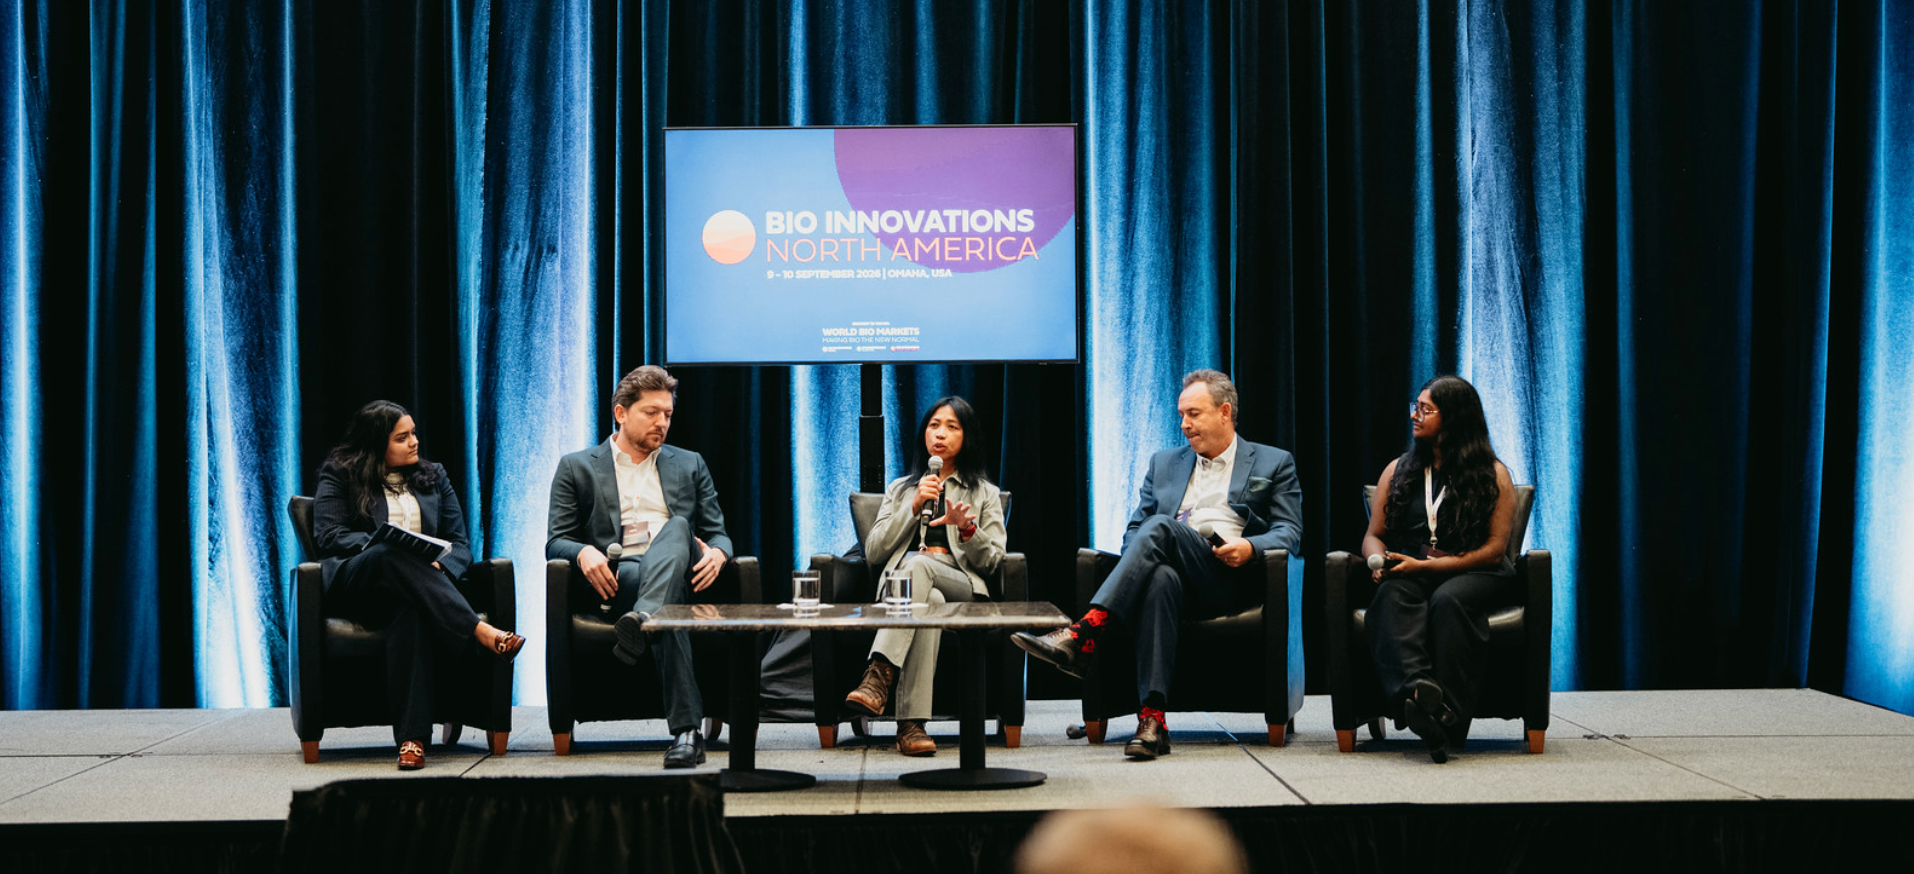
After attending Bio Innovations North America (#BINA36) in Omaha, Nebraska, on Sept 9-10, our biggest takeaway is that the conversation around bio-based chemicals and industrial biotechnology is changing.
There was still plenty of discussion about innovative technologies, feedstocks and new molecules. But much more of the conversation centered on a harder question: How do we actually get these technologies from pilot and demonstration scale into economically sustainable commercial production?
This was particularly evident during the panel on Biomanufacturing Around the World: Lessons for U.S. Scale-ups and International Partnership Opportunities, where Green D Market Analytics joined representatives from Dispersa, Catalyxx and Ontario Genomics moderated by Lux Research. Europe has built an impressive ecosystem for R&D, pilot projects and demonstration plants, but commercial deployment remains difficult when companies face high construction, energy and utility costs. Canada has excellent universities, biotechnology talent, clean electricity and other resources, but much of its investment remains concentrated at the early stages. As Ontario Genomics pointed out, Canadian companies can reach pilot scale and then find that the infrastructure they need for the next stage is elsewhere—taking technology, customers and potentially IP with them.
The USA has some important advantages, particularly abundant agricultural feedstocks, existing chemical and refining infrastructure and competitively priced bio-ethanol. Catalyxx, for example, is using bio-ethanol as the feedstock for renewable n-butanol, n-hexanol and other higher alcohols for coatings, adhesives, flavors and fragrances, cosmetics and personal care. The company believes US ethanol economics can allow these products to compete with conventional oxo-alcohol alternatives without depending on a large green premium.
Feedstock strategy was a recurring theme. Lakril’s technology converts any lactic acid grade— and potentially 3-hydroxypropionic acid — into acrylic acid using a proprietary catalyst, with the objective of producing a molecule-for-molecule replacement for petroleum-derived acrylic acid. The company discussed targeting competitiveness at roughly 40,000 tpa scale rather than assuming customers will permanently pay a sustainability premium.
CellUranics provided another example through its approach to furandicarboxylic acid (FDCA) commercialization. Instead of the more established fructose-to-HMF-to-FDCA pathway, the company is developing a route from glucose through glucaric acid to FDCA. Its reasoning is very much based on commodity chemical economics: glucose is more abundant and lower cost than fructose. CellUranics is now moving toward a 5,000 tpa demonstration plant in China. FDCA already has substantial downstream interest for polyethylene furanoate (PEF) packaging and fibers. The remaining challenge is producing it reliably at the cost and scale required for a commodity polyester value chain.
Biofine North America is developing its first commercial facility in Lincoln, Maine, around forestry residues and non-recyclable paper waste. Its proprietary process breaks lignocellulosic material into intermediates that can ultimately produce levulinic acid, renewable heating fuel, biochar and carbon credits. The planned facility is designed to process approximately 300 metric tpd of feedstock. Importantly, Biofine is targeting feedstocks for which there is currently substantial regional availability and limited competing demand.
Oleo, another start-up company, is developing a platform that converts agricultural residues and woody biomass into oils that can be used in existing HEFA sustainable aviation fuel and renewable diesel infrastructure. Its proposition is to lower feedstock costs sufficiently to improve the economics of renewable fuels and ultimately compete without relying on carbon credits.
Dispersa illustrates how waste streams can support higher-value specialty markets. The company converts food waste, particularly waste oils and sugars, into biosurfactants, initially targeting cleaning products and moving into personal care. Its experience also highlighted an important scale-up issue for Canadian biotechnology companies: pilot and pre-commercial infrastructure and large-scale vessels are often more readily available in the U.S., making stronger cross-border access to infrastructure potentially valuable for both countries.
Another important perspective came from J.M. Smucker, which is evaluating emerging proteins, oils, sweeteners and sustainable packaging. For a major consumer products company, however, interesting technology is only the starting point. Adoption requires technical feasibility, consumer acceptance, regulatory clearance, reliable supply, acceptable economics and alignment across R&D, procurement, operations, engineering, quality and marketing. Its advice to startups is to be transparent about technology readiness and commercialization timelines—and be patient.
Government funding can help technologies reach pilot and demonstration scale but market pull ultimately has to come from customers. Procurement programs, regulations and sustainability commitments can help establish markets, but renewable products still need competitive economics, functionality and reliable supply.
The next phase of the bioeconomy will not be determined simply by who develops the most innovative molecule or process. The winners will be those that successfully connect low-cost feedstocks, scalable processes, infrastructure, financing, regulation and committed customers into commercially viable value chains.
Green D Market Analytics will present its annual Renewable Chemicals and Polymers Market Update on 22 September at the Renewable Materials Conference by Nova-Institut in Siegburg, Germany.
Green D Market Analytics can provide a specialized report highlighting the market for bio-based chemical intermediates and monomers. We provide our clients with confidential reports on the current industry landscape, including new and planned projects. Please contact us at info@greendma.com for more information about our customized client services, detailed market data, and special reports.
The GreenDMA Portal is unique in its ability to provide current data on the renewable chemicals market, including Capacity, Product Profiles, Market Players, Market Share, New Investments, New Plants, Critical Industry News, and analyses. Find out more at greendma.com/portal.
Leave a Reply